1. Introduction: Why Your Previous Budgets Failed (And Why This One Won’t)
Let’s be honest for a moment. If you are reading this, chances are you have tried to budget before. You’ve probably downloaded an app, opened a spreadsheet, or even used the envelope system with the best of intentions. For the first two weeks, you were a machine. You tracked every latte, every grocery run, and every subscription. You felt in control. You felt like the “financial guru” version of yourself had finally arrived.
And then, life happened.
Maybe it was a car repair. Maybe it was a friend’s birthday dinner you didn’t want to miss. Maybe it was just a Tuesday where you were tired, stressed, and decided that tracking $4.50 for a coffee wasn’t worth the mental energy. The crack appeared. Then another. Within a month, the spreadsheet was abandoned, the app notifications were muted, and you were back to wondering where your money went, feeling a familiar mix of guilt and frustration.
You are not broken. Your math isn’t necessarily wrong. The problem is that most budgeting advice treats humans like robots. It assumes that if you just have the right data, you will make the right decisions. But we know that money is emotional. It is tied to our upbringing, our insecurities, our desires, and our stress levels. A budget that ignores the human element is destined to fail because it fights against your nature rather than working with it.
The Definition of a “Realistic” Budget
When we say “realistic,” we don’t mean “bare minimum.” We don’t mean a budget so restrictive that you can never enjoy a movie night or buy a new pair of shoes without a committee meeting. That is a starvation diet, not a financial plan. And just like a starvation diet, it leads to binging later.
A realistic budget is a spending plan that aligns with your actual values, accommodates your imperfect human behavior, and provides enough flexibility to survive a bad month without collapsing. It is a living document, not a stone tablet. It accounts for the fact that you will forget to track things sometimes. It accounts for the fact that your income might fluctuate. It accounts for the fact that you are raising kids, paying a mortgage, or trying to pay off student loans in an economy that often feels designed to keep you broke.
The Cost of Financial Chaos
Why does this matter? Why go through the trouble of building a system that “actually sticks”? Because the cost of not having a realistic budget is far higher than the effort of creating one.
Financial stress is a silent killer. Studies consistently show that money is the number one source of stress for adults. This stress manifests physically—high blood pressure, insomnia, anxiety—and relationally. Couples who fight about money are significantly more likely to divorce. Parents who are financially chaotic pass that anxiety down to their children, creating generational cycles of scarcity mindset.
But beyond the emotional toll, there is a literal price tag on disorganization. Late fees, overdraft charges, high-interest credit card debt, missed investment opportunities, and emergency purchases made at a premium because you didn’t plan ahead—these are the “stupid taxes” we pay for lack of a system. A realistic budget isn’t about restriction; it’s about removing these hidden taxes from your life.
Who This Guide Is For
This guide is written for the person who has failed at budgeting before. It is for the freelancer whose income changes every month. It is for the parent drowning in kid-related expenses. It is for the couple who can’t agree on spending. It is for the high earner who still lives paycheck to paycheck because of lifestyle creep.
We are going to move beyond the basic “income minus expenses equals savings” equation. We are going to dive deep into behavioral psychology, advanced categorization strategies, debt integration, and long-term wealth building. We will cover everything from the neuroscience of impulse buying to the specific Excel formulas that automate your tracking.
By the end of this 50-minute read, you will not just have a budget. You will have a financial operating system. You will understand why you spend, how to optimize your cash flow, and what to do when things go wrong.
Let’s stop renting your financial life and start owning it. Let’s build something real.
2. The Psychology of Money: Rewiring Your Brain for Financial Success
Before we open a single spreadsheet or download an app, we must address the hardware running your financial software: your brain. Most people try to change their spending habits without understanding the neurological and psychological drivers behind those habits. This is why willpower fails. Willpower is a finite resource; systems and psychological reframing are renewable.
The Scarcity Mindset vs. The Abundance Mindset
Your relationship with money likely began long before you earned your first paycheck. It started at the dinner table. Did your parents argue about bills? Did they use money as a reward or a punishment? Did they preach frugality out of fear or out of strategic choice?
These early experiences create “money scripts”—subconscious beliefs that drive your adult behavior. Common destructive scripts include:
- “Money is evil/dirty”: Leading to self-sabotage or under-earning.
- “I’ll never have enough”: Leading to hoarding or panic-spending.
- “More money will solve my problems”: Leading to lifestyle inflation and perpetual dissatisfaction.
- “I deserve this because I worked hard”: Leading to retail therapy as a coping mechanism.
To build a realistic budget, you must identify your scripts. Ask yourself: What emotion am I feeling right before I make an unplanned purchase? Is it boredom? Loneliness? Stress? Pride? If you can identify the trigger, you can interrupt the pattern. A realistic budget includes line items for “mental health” or “entertainment” specifically to address these emotional needs in a controlled way, rather than letting them explode as untracked debt.
The Pain of Paying
Behavioral economists have identified a concept called the “pain of paying.” This refers to the negative emotion we feel when parting with money. Research shows that this pain varies significantly based on the payment method.
- Cash: High pain. You physically see the money leave your hand. The transaction feels “real.”
- Debit Card: Medium pain. The money leaves your account immediately, but the physical sensation is gone.
- Credit Card: Low pain. The transaction is abstracted. You are swiping plastic, not handing over value. The pain is deferred to a future date (the bill), which your present-biased brain discounts heavily.
- Digital Wallets/One-Click Buy: Near-zero pain. Friction is removed entirely. Spending becomes a dopamine hit without the accompanying brake pedal.
Actionable Insight: If you struggle with overspending, you need to artificially increase the “pain of paying.” This doesn’t mean you must go back to cash envelopes forever (though that helps). It means adding friction. Unsave your credit card details from browsers. Turn off Apple Pay for non-essential categories. Force yourself to log in and type the numbers. That extra 30 seconds of friction engages your prefrontal cortex—the logical part of your brain—and gives it time to override the limbic system’s impulse.
Decision Fatigue and Cognitive Load
Every decision you make depletes your mental energy. By 8:00 PM, after making hundreds of micro-decisions at work, parenting, and managing household logistics, your decision-making battery is empty. This is why late-night online shopping is so dangerous. You aren’t making a rational choice; you are making a low-energy choice.
A realistic budget reduces cognitive load by automating decisions in advance. Instead of deciding “Can I afford this dinner?” every Friday night, the budget has already allocated $150 for dining out. The decision was made on Sunday morning when your brain was fresh. Now, Friday night is just execution.
The Pre-Commitment Strategy: Behavioral science tells us that we are better at planning for our future selves than we are at acting in the present. Use this. Set up automatic transfers to savings on payday. Pre-pay bills. Create “rules” for yourself when you are calm (e.g., “I will wait 48 hours for any purchase over $100”). These pre-commitments act as guardrails for when your willpower inevitably runs low.
Identity-Based Budgeting
James Clear, author of Atomic Habits, argues that true behavior change comes from identity change. If your budget says “Save $500” but your identity is “I am a spender who loves nice things,” you will eventually rebel against the budget.
You must shift from outcome-based goals (“I want to save $10,000”) to identity-based goals (“I am the kind of person who values security over status”). Every time you stick to your budget, you are casting a vote for this new identity. Conversely, every time you blow the budget, you reinforce the old identity.
Reframing Exercise: Stop saying “I can’t afford that.” Start saying “That isn’t a priority for me right now.” The first phrase implies deprivation and victimhood. The second implies agency and choice. A realistic budget is a statement of priorities, not a prison sentence.
3. Phase 1: The Financial Autopsy – Understanding Your True Numbers
You cannot navigate to a destination if you don’t know your starting point. Most people think they know where their money goes, but studies show we underestimate our spending by 20-30%. We forget the small stuff. We normalize the subscriptions. We round down the groceries.
Before building the new budget, we must perform a forensic audit of the last 3-6 months. This is not about judgment; it is about data collection.
Step 1: Gather All Data Sources
Do not rely on memory. Do not rely on a single bank statement. Money flows through multiple channels. You need to aggregate:
- Checking account statements (last 3 months minimum)
- Credit card statements (all cards)
- Digital wallet histories (PayPal, Venmo, CashApp)
- Investment account withdrawals
- Cash withdrawal records (this is the hardest to track, see below)
- Loan statements
Step 2: The Categorization Deep Dive
Export these transactions to a spreadsheet or use a dedicated tool. Now, categorize every single transaction. Do not use broad categories like “Miscellaneous” or “Stuff.” Be granular.
Bad Category: Shopping ($400) Good Categories: Clothing ($150), Home Decor ($100), Gifts ($50), Electronics ($100)
Why does granularity matter? Because “Shopping” hides patterns. You might think you have a clothing problem when you actually have a home decor problem. Or you might realize that $200 of that “shopping” was actually gifts for other people, which belongs in a completely different bucket.
Recommended Core Categories for Audit:
- Housing: Rent/Mortgage, Property Tax, HOA, Repairs
- Utilities: Electric, Water, Gas, Internet, Phone, Trash
- Food: Groceries, Dining Out, Coffee/Snacks, Work Lunches
- Transportation: Car Payment, Insurance, Gas, Maintenance, Uber/Lyft, Public Transit
- Health: Insurance premiums, Copays, Medications, Gym, Therapy
- Personal: Clothing, Haircuts, Toiletries, Subscriptions
- Debt: Credit Cards, Student Loans, Personal Loans
- Entertainment: Streaming, Movies, Events, Hobbies
- Gifts/Donations: Holidays, Birthdays, Charity
- Savings/Investments: Emergency Fund, Retirement, Brokerage
Step 3: Calculating True Income
For salaried employees, this is easy: look at your net pay. But for a realistic budget, you must account for variability.
- Freelancers/Gig Workers: Do not budget based on your best month. Calculate your average monthly income over the last 12 months. Then, take the lowest 3 months and average those. Budget based on that number. Any income above this baseline is a bonus to be allocated to debt or savings, not lifestyle.
- Commission-Based: Similar to freelancers. Establish a “base salary” you pay yourself from your business account, and treat commissions as variable upside.
- Overtime/Bonuses: Exclude these from your baseline budget. They are irregular. If you budget expecting overtime and it doesn’t happen, you go into deficit. If it does happen, great—accelerate your goals.
Step 4: Identifying the Leaks
Once categorized, calculate the monthly average for each. Now, compare this to your values.
- The Alignment Test: Look at your top 3 spending categories. Do they reflect what you say is important? If you say “Family is #1” but you spend 3x more on solo gaming subscriptions than family outings, there is a misalignment.
- The Zombie Expenses: Identify recurring charges for services you no longer use or value. Gym memberships you haven’t visited in 6 months. Three streaming services when you only watch one. Insurance policies with deductibles you couldn’t afford if you actually had a claim. These are pure waste.
- The Inflation Creep: Compare Month 1 to Month 6. Did your grocery bill creep up $200 without a change in family size? Did your utility bill rise? Adjust your baseline expectations accordingly. A realistic budget acknowledges inflation; it doesn’t pretend prices are what they were in 2019.
Step 5: Calculating Net Worth (The Big Picture)
Budgeting is cash flow; net worth is wealth. You need both. List all assets (cash, investments, home equity, vehicle value) and all liabilities (mortgages, loans, credit cards). Assets minus Liabilities = Net Worth.
Tracking this quarterly alongside your monthly budget provides crucial context. You might have a tight cash flow month, but if your net worth is trending up, you are winning. Conversely, you might have plenty of cash flow but a declining net worth due to depreciating assets or accumulating debt.
4. Phase 2: Choosing Your Budgeting Weapon – Methods Compared
There is no “best” budget. There is only the best budget for you. Different personalities, income types, and life stages require different frameworks. Let’s analyze the major methodologies in depth.
1. Zero-Based Budgeting (ZBB)
Philosophy: Income – Expenses = $0. Every dollar has a job. Best For: Detail-oriented people, those with tight margins, debt destroyers.
How It Works: You list all income. Then you allocate every single dollar to an expense, savings, or debt category until you reach zero. If you earn $4,000, you assign exactly $4,000. If you have $200 left over, it is not “extra”; it is unassigned. You must give it a job (e.g., “Extra Debt Payment” or “Emergency Fund”).
Pros:
- Maximum intentionality. No money floats aimlessly.
- Excellent for getting out of debt quickly.
- Highlights waste immediately.
Cons:
- High maintenance. Requires frequent adjustments.
- Can feel restrictive or obsessive.
- Difficult for variable income.
Realistic Adaptation: Don’t ZBB down to the penny if it makes you miserable. Group small variables into a “Buffer” category. If you usually spend $300 on miscellaneous stuff, budget $350. The extra $50 is your ZBB cushion for when you forget to track a $12 purchase.
2. The 50/30/20 Rule
Philosophy: Simplicity and balance. Best For: Beginners, stable income earners, people who hate tracking details.
How It Works:
- 50% Needs: Housing, utilities, groceries, minimum debt payments, insurance.
- 30% Wants: Dining out, hobbies, travel, subscriptions, shopping.
- 20% Savings/Debt: Emergency fund, retirement, extra debt payoff.
Pros:
- Extremely simple mental model.
- Built-in permission to spend (30% is significant!).
- Easy to adjust as income grows.
Cons:
- Ratios may not fit high-cost-of-living areas (where 50% needs is impossible).
- Lacks granularity. You could blow the entire 30% on video games and starve your savings within that bucket.
- Doesn’t account for aggressive debt payoff timelines.
Realistic Adaptation: Treat the ratios as targets, not laws. In expensive cities, it might be 60/20/20. During debt crunches, it might be 50/10/40. The framework remains; the percentages flex.
3. The Envelope System (Cash Stuffing)
Philosophy: Physical friction prevents overspending. Best For: Chronic overspenders, visual learners, variable income households.
How It Works: Withdraw cash for variable categories (groceries, entertainment, gas). Put the cash in labeled envelopes. When the envelope is empty, you stop spending in that category until next month. Fixed bills are paid digitally.
Pros:
- Impossible to overspend (unless you steal from another envelope).
- Visceral connection to money.
- Great for couples to align on spending limits visually.
Cons:
- Security risk (carrying cash).
- Inconvenient in a digital world.
- Doesn’t build credit history.
- Hard to track for rewards points.
Realistic Adaptation: Hybrid Envelope System. Use cash for your top 2-3 problem categories (usually food and entertainment). Use debit/cards for everything else. You don’t need to stuff every category to get the psychological benefit.
4. Values-Based Budgeting
Philosophy: Spend extravagantly on what you love; cut mercilessly on what you don’t. Best For: Non-conformists, minimalists, people recovering from restrictive diets.
How It Works: Identify your top 3-5 values (e.g., Travel, Education, Health). Allocate generous funding to these. Cut all other discretionary spending to the bare minimum. Unlike 50/30/20, there is no standard “wants” bucket. Your “wants” are highly specific.
Pros:
- High satisfaction. You never feel deprived in areas that matter.
- Sustainable long-term because it aligns with identity.
- Eliminates comparison spending.
Cons:
- Requires deep self-knowledge.
- Can look “weird” to outsiders.
- Risk of neglecting maintenance categories (like car repairs) if they aren’t a “value.”
Comparison Matrix
| Feature | Zero-Based | 50/30/20 | Envelope | Values-Based |
|---|---|---|---|---|
| Effort Level | High | Low | Medium | Medium |
| Flexibility | Low | High | Low | High |
| Debt Payoff Speed | Fastest | Moderate | Fast | Variable |
| Best For Personality | Type A / Controller | Balanced / Busy | Impulsive / Visual | Creative / Independent |
| Tech Requirement | Spreadsheet/App | Mental Math | Physical Cash | Hybrid |
Recommendation: Start with Zero-Based Budgeting for the first 3 months to establish baseline awareness. Then, transition to a Hybrid Model: Use ZBB principles for fixed costs and debt, but use percentage caps (like 50/30/20) for variable spending to reduce daily decision fatigue.
5. Phase 3: Building Your Custom Budget Framework
Now we synthesize the audit and the method into a functional document. Whether you use YNAB, Excel, or a notebook, the structure should follow this logic.
The Four Walls Priority
Before you budget for vacations or investments, you must secure the “Four Walls.” These are non-negotiable. If money is tight, these get paid first. Everything else waits.
- Food: Basic groceries. Not restaurants. Not DoorDash. Rice, beans, vegetables, protein.
- Utilities: Lights, water, heat. Keep the lights on and the water running.
- Shelter: Rent or mortgage. Keep the roof overhead.
- Transportation: Gas or bus fare to get to work. Keep the income flowing.
Note: Minimum debt payments are often considered a fifth wall, but strictly speaking, you can defer them in a true crisis (with consequences). Food/Shelter/Utilities/Transport are immediate survival.
The Budget Template Structure
Create columns for: Category | Budgeted Amount | Actual Spent | Difference | Notes
Section A: Income
- Primary Job (Net)
- Side Hustle (Conservative Estimate)
- Other (Child support, alimony, etc.)
- Total Available
Section B: Giving/Saving (Pay Yourself First)
- Emergency Fund Contribution
- Retirement Match
- Charitable Giving
- Why here? Because if you wait until the end of the month to save, there will be nothing left. Saving is an expense, not a residual.
Section C: The Four Walls + Fixed Obligations
- Rent/Mortgage
- Utilities
- Insurance (Health, Auto, Life)
- Minimum Debt Payments
- Childcare/Tuition
- Phone/Internet
Section D: Variable Essentials
- Groceries
- Gas/Transit
- Household Supplies
- Medical Co-pays
Section E: Quality of Life (The Fun Stuff)
- Dining Out
- Entertainment
- Personal Care
- Clothing
- Gifts
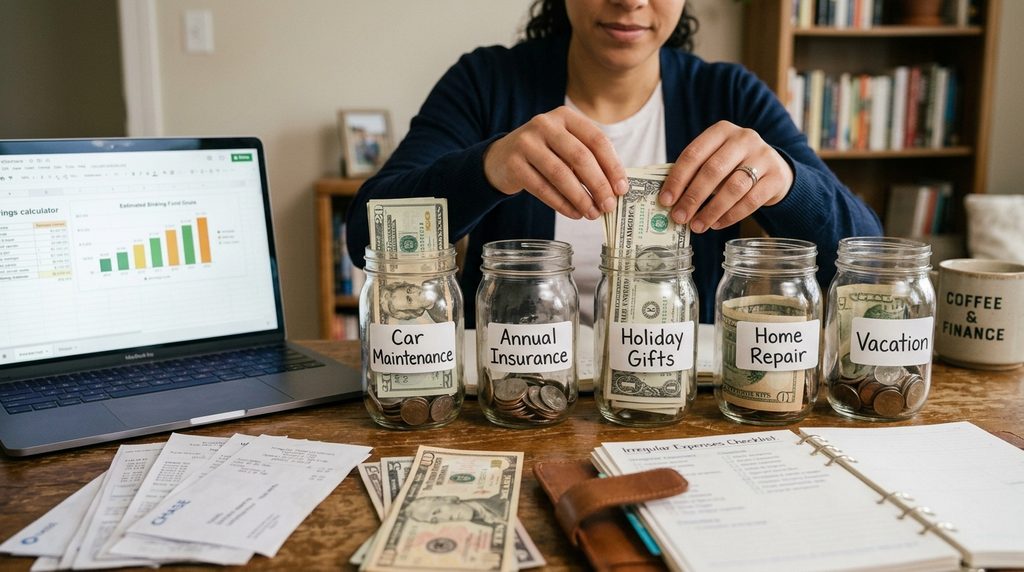
Section F: Sinking Funds (Crucial Section)
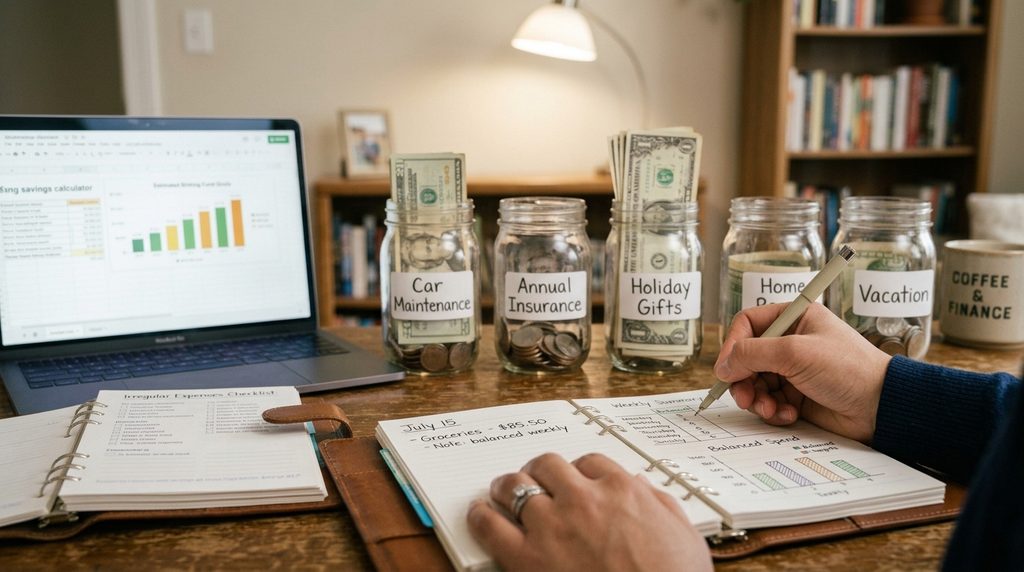
- Car Maintenance
- Home Repair
- Annual Subscriptions
- Holiday Gifts
- Vacation
- See Section 8 for detailed explanation
Setting the Initial Numbers
Do not guess. Use the averages from your Phase 1 Audit as your starting baseline.
- If you spent $600 on groceries avg, budget $600. Do not arbitrarily cut to $400 yet. That sets you up for failure.
- Once you have tracked accurately for 2-3 months at the baseline, then look for optimization opportunities.
- The 10% Challenge: After establishing baselines, challenge yourself to reduce variable categories by 10%. $600 groceries becomes $540. This is achievable without misery.
Handling Variable Income in the Framework
If your income fluctuates, your budget must be dynamic.
- Calculate Baseline Expenses: Total of Sections B, C, and D. This is your “Survival Number.”
- Prioritize Expenses: Rank Section E and F items by importance.
- The Waterfall Method: When income arrives, fill buckets in order.
- Income < Survival Number? Use emergency fund or defer non-essentials.
- Income = Survival Number? Cover basics only.
- Income > Survival Number? Fund Section E/F in priority order.
- Surplus? Extra debt payoff or savings.
Never assume next month’s income will cover this month’s overspending. Live on last month’s income if possible (the YNAB Rule #1). If you can’t, maintain a “Income Smoothing” buffer account. Deposit excess from good months; withdraw in lean months.
6. The Art of Expense Tracking: Data Without Obsession
Tracking is the engine of any budget, but it is also the most common point of failure. Why? Because people confuse tracking with judgment. They track to punish themselves for spending $15 on lunch, rather than tracking to understand their cash flow patterns. A realistic budget requires a tracking system that provides high-fidelity data with low emotional friction.
Choosing Your Tracking Medium
There is no moral superiority in using a spreadsheet over an app, or vice versa. The best tool is the one you will actually use consistently.
Spreadsheets (Excel/Google Sheets):
- Best For: Control freaks, privacy advocates, complex variable income, those who want to build custom formulas.
- Pros: Infinite customization, no subscription fees, complete data ownership, forces active engagement with numbers.
- Cons: Manual entry can be tedious, requires setup time, no automatic bank syncing (unless you use paid add-ons), mobile experience is often clunky.
- Realistic Tip: Create a “Quick Entry” tab on your phone’s home screen. Use Google Forms linked to your sheet for instant logging while at the store. This reduces the friction of opening a heavy spreadsheet file.
Budgeting Apps (YNAB, Mint/Credit Karma, Monarch, Copilot):
- Best For: Automation seekers, couples sharing finances, visual learners, busy professionals.
- Pros: Automatic transaction import, real-time balance updates, goal tracking features, mobile-first design.
- Cons: Subscription costs ($10-$15/month), privacy concerns (bank-level access), categorization errors require manual fixing, can create passive detachment from money.
- Realistic Tip: Turn off “auto-categorize” if it makes you lazy. Force yourself to review and confirm every transaction. The 2 minutes of review is where the behavioral change happens. If you just let the app sort everything, you aren’t budgeting; you’re just watching a dashboard.
The Analog Hybrid (Notebook + Digital):
- Best For: Tactile learners, those recovering from digital burnout, simple budgets.
- Method: Carry a small notebook. Write down every expense immediately. Transfer to digital weekly for analysis.
- Why It Works: The physical act of writing creates a stronger memory imprint than tapping a screen. Studies show that handwriting engages different neural pathways associated with retention and processing.
Frequency Matters More Than Precision
You do not need to track to the penny every single day to succeed. In fact, daily micro-tracking can lead to obsession and burnout.
- Daily: Quick log (mental note or app entry). Don’t analyze, just record.
- Weekly: The “Money Date.” Set aside 20 minutes every Sunday (or payday) to reconcile accounts, categorize transactions, and check progress against the budget. This is non-negotiable.
- Monthly: Deep dive. Review trends, adjust categories, celebrate wins, plan for upcoming irregular expenses.
The 80/20 Rule of Tracking: Focus your energy on the 20% of categories that cause 80% of your variance. If you always spend exactly $1,200 on rent and $150 on internet, stop obsessively checking those. Focus your tracking discipline on Groceries, Dining Out, and Shopping—these are the leaky buckets.
Handling Cash and Shared Expenses
Cash is the black hole of budgeting. Once it leaves your hand, it ceases to exist in your digital records.
- Solution: Withdraw cash only for specific budgeted categories. When you withdraw $200 for groceries, immediately log it as a “Grocery Transfer” in your tracker. Now the money exists digitally even though it’s physically gone. When you spend it, you don’t need to log the individual items because the transfer already accounted for the budget impact.
Shared expenses (roommates, partners) create friction.
- Solution: Use apps like Splitwise or Tricount for shared costs, but keep your personal budget separate. Reimbursements should be treated as income/inflow in your personal tracker only when received. Do not budget for money you haven’t been reimbursed for yet.
7. Debt Destruction: Integrating Repayment Into Your Budget
Debt is not just a number; it is a monthly cash flow anchor. A realistic budget must treat debt repayment as a dynamic line item, not a static bill. Most budgets fail because they list minimum payments as fixed costs, ignoring the opportunity cost of carrying that debt.
Minimum Payments vs. Strategic Payoff
Your budget should have two lines for each debt:
- Minimum Payment: Fixed obligation. Goes in “Fixed Obligations.”
- Extra Payment: Variable strategy. Goes in “Savings/Debt Acceleration.”
Never budget only the minimum unless you are in survival mode. The extra payment is what changes your trajectory. But how much extra? This depends on your chosen payoff method.
The Avalanche Method (Mathematically Optimal)
- Strategy: List debts by interest rate (highest to lowest). Pay minimums on all. Throw all extra money at the highest rate.
- Psychological Profile: Logical, patient, motivated by efficiency.
- Budget Impact: Requires discipline. You might pay $500 extra to a credit card at 24% APR while ignoring a student loan at 4%. Progress feels slow initially because balances don’t drop fast, but interest savings are massive long-term.
The Snowball Method (Behaviorally Optimal)
- Strategy: List debts by balance (smallest to largest). Pay minimums on all. Throw all extra money at the smallest balance.
- Psychological Profile: Needs quick wins, easily discouraged, motivated by momentum.
- Budget Impact: Faster psychological relief. Eliminating a $500 medical bill in month 2 feels better than reducing a $20,000 student loan by $500. Research shows snowball users are more likely to stick with their payoff plan despite paying slightly more interest overall.
Integrating Debt Windfalls
When you get a tax refund, bonus, or gift, your budget must have a pre-decided rule. Do not let windfalls sit in checking.
- Rule Example: “50% Debt / 30% Savings / 20% Fun.”
- Why Fun? Depriving yourself entirely of windfall joy leads to rebellion. Allocating 20% for guilt-free spending ensures the other 80% gets deployed strategically without resentment.
The Debt Emergency Fund Paradox
Should you save or pay debt first? The realistic answer is both, sequentially.
- Save $1,000 starter emergency fund (cash).
- Attack high-interest debt (>7%) aggressively.
- Build full emergency fund (3-6 months expenses).
- Attack lower-interest debt.
Skipping step 1 means one flat tire forces you back onto credit cards, undoing months of payoff progress. The $1,000 buffer is insurance for your debt payoff plan.
8. Sinking Funds & Irregular Expenses: The Secret to Consistency
This is the single most important concept for making a budget stick. Most budgets fail because they treat monthly expenses as the only reality. But life is not monthly. Car tires blow out in July. Christmas comes in December. Annual insurance premiums hit in March.
If you budget $0 for these in non-expense months, you will be blindsided. If you try to pay them out of that month’s income, you will go into deficit.
What Is a Sinking Fund?
A sinking fund is a savings category specifically designated for a known future expense. You “sink” money into it gradually over time so that when the bill arrives, the money is already there.
Setting Up Sinking Funds
Review your last 12 months of bank statements. Identify every non-monthly expense:
- Car Registration: $150/year → Save $13/month
- Amazon Prime: $139/year → Save $12/month
- Holiday Gifts: $600/year → Save $50/month
- Vet Visits: $400/year → Save $33/month
- Home Maintenance: $1,200/year → Save $100/month
Add these monthly amounts to your budget as fixed expenses. Treat them with the same respect as rent. When the actual bill comes, transfer from the sinking fund to checking to pay it. The budget remains balanced because you planned for it.
The “Buffer” Category
Even with sinking funds, surprises happen. Budget a “Miscellaneous/Buffer” category of $100-$200/month. This is your shock absorber. If you don’t use it, roll it over. After 6 months, you have a $600-$1,200 cushion for true emergencies that don’t fit existing categories. This prevents small surprises from derailing your entire financial plan.
Digital vs. Physical Sinking Funds
- Digital: Sub-accounts or tags within your budgeting app. Best for organization and earning interest.
- Physical: Separate savings accounts at different banks. Best for temptation control. If your vacation fund is at a different bank with no debit card, you can’t impulse-spend it.
- Hybrid: Keep short-term sinking funds (next 3 months) in checking/sub-account for liquidity. Keep long-term funds (6+ months out) in HYSA or separate bank.
9. Behavioral Economics: Hacking Your Willpower
Willpower is a muscle that fatigues. Systems are structures that endure. To make your budget stick, you must design your environment to make good choices easy and bad choices hard.
Friction Design
- Increase Friction for Spending: Unsubscribe from marketing emails. Delete shopping apps. Remove saved payment methods. Require password entry for purchases over $50. Put a 24-hour hold rule on non-essentials.
- Decrease Friction for Saving: Automate transfers on payday. Use round-up apps. Make savings accounts invisible (no debit card, no online banking login on phone).
Implementation Intentions
Vague goals fail. Specific “if-then” plans succeed.
- Bad Goal: “I will spend less on food.”
- Implementation Intention: “IF I feel hungry at 3 PM at work, THEN I will eat the apple I packed instead of ordering DoorDash.”
- Bad Goal: “I will save more.”
- Implementation Intention: “IF my paycheck hits on Friday, THEN $500 automatically transfers to savings before I check my balance.”
Write down 3-5 implementation intentions for your top spending triggers. Post them where you’ll see them (fridge, wallet, phone wallpaper).
Social Accountability
Money is taboo, which makes accountability rare. Break the taboo safely.
- Accountability Partner: Find one trusted friend with similar goals. Weekly check-in: “What did you stick to? Where did you slip?” No judgment, just data.
- Online Communities: r/personalfinance, Budget Buddies Facebook groups. Anonymity allows honest sharing without shame.
- Professional Help: Financial therapist or coach if money trauma runs deep. Sometimes the barrier isn’t math; it’s unresolved emotional pain.
Reward Substitution
You cannot eliminate the desire for reward; you can only redirect it.
- Old Pattern: Stress → Online shopping → Dopamine → Guilt.
- New Pattern: Stress → 10-minute walk + tea → Calm → Review budget → Sense of control. Identify the emotional need behind the spending. Find a free or low-cost alternative that meets the same need. Boredom? Library books or podcasts. Loneliness? Free community events or calling a friend. Status? Skill-building or volunteering.
10. Advanced Budgeting: Optimizing for Wealth, Not Just Survival
Once your budget is stable and you have mastered the basics of cash flow management, it is time to shift from defensive financial planning to offensive wealth building. A realistic budget that sticks doesn’t just keep you afloat; it actively builds your net worth. This phase transforms your budget from a tracking tool into a strategic asset allocation engine.
The Hierarchy of Financial Optimization
Not all dollars are created equal. When you have surplus cash flow, where should it go? Following a strict hierarchy ensures maximum mathematical efficiency while maintaining psychological safety.
- Employer Match (Free Money): Always max this out first. It is an instant 100% return on investment. No market strategy beats this.
- High-Interest Debt (>7% APR): Guaranteed return equal to the interest rate. Paying off 20% credit card debt is mathematically identical to earning a risk-free 20% return.
- Emergency Fund Completion: 3-6 months of essential expenses in a High-Yield Savings Account (HYSA). This prevents future debt accumulation.
- Tax-Advantaged Retirement Accounts: Max out Roth IRA or Traditional IRA up to limits. The tax savings effectively boost your returns by 20-30% depending on your bracket.
- HSA (Health Savings Account): If eligible, this is triple-tax-advantaged. Treat it as a stealth retirement account, not a medical checking account.
- Taxable Brokerage Accounts: For goals beyond retirement age or after maxing tax-advantaged space.
- Lifestyle Upgrades / Fun: Only after steps 1-6 are funded. This ensures your “fun” money is truly guilt-free because your future is secure.
Tax-Efficient Budgeting Integration
Your budget must account for taxes as a variable expense, not just a payroll deduction.
- Freelancers/Self-Employed: Budget 25-30% of gross income into a separate “Tax Sinking Fund.” Never mix this with operating capital. Quarterly estimated payments should be automated from this fund.
- W-2 Employees: Review your W-4 annually. Over-withholding is an interest-free loan to the government. Adjust withholding so you break even at tax time, freeing up monthly cash flow for sinking funds or investments.
- Deductible Expenses: Track business expenses meticulously if self-employed. Every deductible dollar reduces taxable income, effectively saving you 20-37 cents on the dollar. Use apps like Keeper or Hurdlr to automate this tracking alongside your personal budget.
Asset Allocation Within the Budget
Your budget dictates your savings rate; your asset allocation dictates your growth rate. These two must work in tandem.
- Age-Based Rule of Thumb: Subtract your age from 110. That percentage should be in equities; the rest in bonds/cash. Adjust based on risk tolerance and timeline.
- Rebalancing as a Budget Line Item: Set aside time quarterly to rebalance. Selling high and buying low isn’t just a market tactic; it’s a disciplined budgeting habit. Automate this if possible through target-date funds or robo-advisors.
- Location Efficiency: Place high-growth assets in Roth accounts (tax-free growth), income-generating assets in Traditional accounts (tax-deferred), and tax-efficient index funds in taxable accounts. Your budget’s contribution amounts should reflect this optimization.
Scaling Income Without Lifestyle Creep
The greatest threat to a wealth-building budget is Parkinson’s Law: expenses rise to meet income. To counter this, implement automatic escalation rules.
- The 50% Raise Rule: Any raise, bonus, or side hustle income increase gets split 50/50. Half improves lifestyle immediately (maintaining motivation); half accelerates wealth goals. This satisfies both the present and future self.
- Invisible Raises: Increase retirement contributions automatically every January by 1%. You won’t feel the difference in take-home pay, but over 20 years, this compounds massively.
- Windfall Protocol: As mentioned earlier, pre-decide windfall allocation. Write it down. Stick to it. Emotionally, a $5,000 bonus feels like “play money.” Mathematically, invested at 8% for 30 years, it’s worth $50,000. Respect the math.
11. Troubleshooting: What to Do When Life Happens
A realistic budget anticipates failure. Perfection is impossible; resilience is mandatory. Here is how to handle the inevitable disruptions without abandoning your system entirely.
The Monthly Reset Ritual
Every month will have variances. Some categories will be over; others under. This is normal.
- Do Not Roll Over Overspending Automatically: If you overspend $100 on groceries, do not simply add it to next month’s grocery budget. This masks the problem. Instead, cover it from your Buffer category or reduce another discretionary category this month. Feel the consequence now, not later.
- Analyze Variances >10%: Small variances are noise. Large variances signal either a budgeting error (underestimated cost) or a behavioral issue (impulse spending). Investigate before adjusting.
- Celebrate Underspending Wisely: If you save $200 on dining out, don’t automatically spend it elsewhere. Allocate 50% to debt/savings and 50% to fun. Reinforce the positive behavior while still enjoying the reward.
Handling Income Shocks
Job loss, reduced hours, or client cancellation require immediate triage.
- Pause All Non-Essentials: Immediately stop sinking fund contributions (except emergency fund), retirement extras, and fun spending.
- Activate Emergency Fund: This is what it’s for. Do not feel guilty. Feel prepared.
- Negotiate Fixed Costs: Call providers. Ask for hardship programs. Defer non-critical maintenance. Reduce insurance deductibles temporarily if cash flow is critical (revert when stable).
- Temporary Survival Budget: Strip down to Four Walls only. Communicate transparently with family/partners. This is a season, not a permanent state.
- Income Generation Sprint: Freelance, sell items, gig work. Treat finding income as a full-time job until stabilized.
Handling Expense Shocks
Medical emergencies, car repairs, or home disasters test your sinking funds and emergency reserves.
- Use Designated Funds First: Car repair? Use Car Maintenance sinking fund. Medical bill? Use HSA or Health sinking fund.
- Replenish Priority: After using a sinking fund, your next budget priority is refilling it before resuming other goals. An empty sinking fund is a future crisis waiting to happen.
- Insurance Review Post-Shock: Did your coverage fail? Adjust premiums/deductibles immediately. A shock reveals gaps; fix them before the next one.
Relationship Conflicts About Money
Budgets expose value differences. Conflict is data, not disaster.
- Scheduled Money Talks: Never discuss money during arguments or stress. Schedule weekly/biweekly calm reviews. Use “I feel” statements, not accusations.
- Autonomy Allowances: Each partner gets a no-questions-asked personal spending amount. This preserves individuality within shared finances. Arguing over $20 coffee purchases destroys trust; autonomy prevents it.
- Shared Goals Visualization: Create a vision board or spreadsheet showing progress toward shared dreams (house, travel, retirement). Remind each other why you’re budgeting. Connection combats conflict.
- Professional Mediation: If conversations consistently escalate, see a financial therapist. Money conflicts often mask deeper relational issues. Fix the root, not just the spreadsheet.
Burnout Recovery
If you’ve tracked perfectly for 6 months and suddenly can’t look at your budget, you’re burned out.
- Take a Tracking Sabbatical: Pause detailed tracking for 2-4 weeks. Maintain minimums and auto-transfers only. Rest resets discipline.
- Simplify Temporarily: Switch from zero-based to 50/30/20 for a month. Reduce cognitive load while maintaining structure.
- Reconnect With Purpose: Review your “Why.” Look at debt payoff progress charts. Remember the freedom you’re building. Motivation follows meaning.
- Adjust Standards: Maybe daily tracking isn’t sustainable long-term. Weekly might be your realistic baseline. Honor your capacity. Consistency at 80% effort beats perfection at 100% followed by quitting.
12. Tools of the Trade: Apps, Spreadsheets, and Analog Systems
Technology serves the budget, not vice versa. Choose tools that match your personality and life stage. Re-evaluate annually as needs change.
Digital App Ecosystem
| App | Best For | Cost | Key Feature | Limitation |
|---|---|---|---|---|
| YNAB | Zero-based, debt payoff, behavioral change | $14.99/mo | Proactive budgeting philosophy | Steep learning curve |
| Monarch Money | Couples, comprehensive net worth | $14.99/mo | Beautiful UI, collaborative features | Newer platform, fewer integrations |
| Copilot | Apple users, automation lovers | $9.99/mo | AI categorization, sleek design | iOS/Mac only |
| PocketGuard | Simple “in my pocket” view | Free/$7.99/mo | Shows spendable cash instantly | Less granular control |
| Goodbudget | Envelope system digitalized | Free/$8/mo | Virtual envelopes, syncs across devices | Manual entry preferred |
| Tiller | Spreadsheet lovers wanting automation | $6.58/mo | Auto-feeds bank data to Google Sheets | Requires spreadsheet skills |
Spreadsheet Templates
For those who want control without subscription fatigue:
- Vertex42 Free Budget Templates: Reliable, classic designs. Good starting point.
- Tiller Community Templates: User-created advanced sheets with macros.
- DIY Build: Create your own. Forces deep understanding of your numbers. Include tabs for: Monthly Budget, Annual Overview, Net Worth Tracker, Debt Payoff Calculator, Sinking Fund Tracker.
Spreadsheet Best Practices:
- Use data validation dropdowns for categories to prevent typos.
- Conditional formatting to highlight overspending visually.
- Protect formula cells to prevent accidental deletion.
- Backup to cloud storage automatically.
- Create a mobile-friendly “Quick Entry” sheet synced to main workbook.
Analog & Hybrid Systems
- Bullet Journal Budgeting: Combine task management with finance. Monthly logs, migration rituals, habit trackers. Highly customizable, tactile satisfaction.
- Cash Envelopes + Digital Tracking: Physical cash for problem categories; app for everything else. Best of both worlds.
- Whiteboard Budget: Visual family accountability. Update weekly together. Makes money tangible for kids/spouses.
- Receipt Shoebox Method: Old school but effective. Sort receipts weekly. Forces confrontation with spending. Digitize monthly for records.
Automation Stack
Maximize efficiency by connecting tools:
- Bank Feeds: Plaid/Yodlee integration for auto-import.
- Bill Pay Automation: Autopay fixed bills from dedicated checking account.
- Transfer Rules: Auto-move surplus to savings/debt on specific dates.
- Expense Alerts: Set thresholds in banking apps for real-time notifications.
- Net Worth Trackers: Empower or Personal Capital for holistic view beyond monthly cash flow.
Security Note: Always use unique passwords, 2FA, and monitor accounts weekly. Automation convenience shouldn’t compromise security vigilance.
13. Common Budgeting Myths vs. Facts
Misinformation derails more budgets than poor math. Let’s dismantle the most pervasive myths.
Myth 1: “Budgeting Means Never Having Fun”
Fact: Budgeting means having fun guilt-free. By allocating specific funds for enjoyment, you remove anxiety from spending. Restriction breeds rebellion; planned indulgence sustains discipline. A budget without fun is a punishment, not a plan.
Myth 2: “I Need to Be Perfect to Succeed”
Fact: Consistency beats perfection. Missing a day of tracking or overspending once doesn’t ruin your progress. The budget is a compass, not a judge. Course-correct and continue. Progress is nonlinear.
Myth 3: “Only Low-Income People Need Budgets”
Fact: High earners often live paycheck-to-paycheck due to lifestyle inflation. Budgeting at higher incomes focuses on optimization, tax strategy, and wealth acceleration rather than survival. Complexity increases with income; systems become more necessary, not less.
Myth 4: “Debt Is Always Bad”
Fact: Strategic debt (mortgage, business loans, education with ROI) can build wealth. Toxic debt (high-interest consumer debt) destroys it. Distinguish between leverage and liability. Budget accordingly.
Myth 5: “Apps Will Fix My Spending”
Fact: Tools amplify existing habits. If you’re disorganized digitally, an app creates organized chaos. Fix behaviors first; technology second. The app doesn’t make decisions; you do.
Myth 6: “Emergency Funds Are Waste Because They Earn Low Interest”
Fact: Emergency funds aren’t investments; they’re insurance. Their ROI isn’t yield; it’s avoided disaster costs. A $1,000 emergency fund prevents $5,000 in credit card debt during a crisis. That’s a 400% return.
Myth 7: “Couples Should Merge Everything”
Fact: Financial intimacy doesn’t require financial fusion. Many successful couples maintain separate accounts with joint contributions. Autonomy preserves individuality; collaboration achieves shared goals. There’s no universal rule; find what works for your relationship.
Myth 8: “Budgeting Takes Too Much Time”
Fact: Initial setup takes hours; maintenance takes minutes weekly. Automation reduces ongoing effort. The time invested prevents hundreds of hours spent stressing about money later. Efficiency compounds.
Myth 9: “Kids Are Too Young to Understand Budgets”
Fact: Financial literacy starts early. Age-appropriate involvement builds lifelong habits. Toddlers learn needs vs. wants. Teens manage allowances. Young adults co-create household budgets. Modeling matters more than lecturing.
Myth 10: “Once I’m Debt-Free, I Can Stop Budgeting”
Fact: Budgeting evolves; it doesn’t end. Post-debt, focus shifts to wealth building, philanthropy, legacy planning. Complacency after debt freedom leads to new debt. Lifelong stewardship requires lifelong systems.
14. Real-World Case Studies: Budgeting in the Trenches
Theory is clean; reality is messy. To truly understand how a realistic budget functions across different life stages and financial situations, we must examine specific, detailed case studies. These are not hypothetical scenarios but composites of real financial journeys that illustrate the application of principles under pressure. Each case study includes the initial state, the intervention strategy, the obstacles encountered, and the long-term outcome.
Case Study 1: The High-Earner Paycheck-to-Paycheck Professional
Profile: Sarah, 32, Senior Software Engineer. Gross Income: $145,000/year. Net Monthly: ~$8,200. Initial State: Despite earning nearly $100k net annually, Sarah had $18,000 in credit card debt, zero emergency fund, and felt perpetually broke. Her spending was invisible—subscriptions she didn’t use, daily $15 coffees, impulse Amazon purchases, and “treat yourself” dinners after stressful sprints. She tracked nothing, assuming her salary would absorb everything. The Intervention:
- Financial Autopsy: Revealed $2,800/month in untracked discretionary spending. Identified $450/month in zombie subscriptions.
- Zero-Based Reset: Allocated every dollar. Discovered she could pay off credit cards in 14 months using Avalanche method while still funding 15% retirement match.
- Friction Implementation: Deleted shopping apps, unsubscribed from marketing emails, instituted 48-hour rule for purchases >$75.
- Sinking Funds Created: For annual software conference ($2,500), holiday gifts ($1,200), and car maintenance ($800). Obstacles: First month was brutal. Withdrawal from dopamine-driven spending caused irritability. Felt deprived despite having more disposable income than ever. Almost quit during week 3 when a friend’s bachelorette party conflicted with new grocery budget. Resolution: Used Buffer category for bachelorette trip without guilt. Celebrated first credit card payoff milestone with planned $200 spa day (budgeted). By month 6, spending became automatic. By month 14, debt-free with $15,000 emergency fund built. Key Takeaway: High income amplifies bad habits faster than low income. Visibility precedes control. Friction design is non-negotiable for impulse spenders regardless of income level.
Case Study 2: The Variable-Income Freelance Couple
Profile: Marcus & Elena, 28 & 30, Graphic Designer + Copywriter. Combined Income: $3,500–$9,000/month. No benefits, no retirement match. Initial State: Feast-or-famine cycles caused chronic anxiety. Good months funded lifestyle inflation; bad months triggered credit card reliance. No system to smooth income volatility. Argued constantly about money because neither knew true cash position. The Intervention:
- Baseline Calculation: Averaged lowest 6 months = $4,200. This became their “Survival Number.”
- Income Smoothing Account: Opened separate checking account. All income deposited here. Paid themselves fixed $4,200 monthly transfer to operating account. Surplus stayed in smoothing account as buffer.
- Priority-Based Waterfall Budget: Operating account funded Four Walls → Minimum Debts → Sinking Funds → Retirement (SEP IRA) → Quality of Life. Only when smoothing account held 3 months’ expenses did they increase baseline pay.
- Weekly Money Dates: Mandatory Sunday syncs to review smoothing account balance, adjust upcoming month’s allocations, and align on priorities. Obstacles: Resisted limiting good-month spending. Felt punished for success. Smoothing account grew slowly; temptation to raid it during lean months was intense. Retirement contributions inconsistent. Resolution: Automated SEP IRA contributions at 10% of baseline income, not actual. Made retirement non-negotiable like rent. After 8 months, smoothing account hit $12,600 (3 months’ expenses). Increased baseline pay by $500/month. Arguments decreased 90% as transparency increased. Key Takeaway: Variable income requires artificial stability. Separating income receipt from spending allocation is critical. Consistency in foundational categories (debt, retirement) matters more than consistency in total spending.
Case Study 3: The Single Parent Rebuilding After Divorce
Profile: James, 41, Teacher. Net Income: $3,800/month. Child support received: $600. Total: $4,400. Initial State: Post-divorce financial trauma. Alimony payments reduced his take-home. Felt resentment toward budgeting as symbol of loss. Overspent on kids to compensate emotionally. Ignored own needs until crisis point. Credit score dropped 120 points. The Intervention:
- Values-Based Reframe: Identified core values: Stability for Kids, Personal Healing, Long-Term Security. Budget structured around these, not deprivation.
- Four Walls Plus: Added “Kids’ Emotional Needs” ($150/month) and “Therapy/Self-Care” ($100/month) as non-negotiable line items. Removed guilt from essential self-investment.
- Debt Snowball Adaptation: Prioritized small medical bills from divorce proceedings first for psychological wins, then attacked high-interest credit cards.
- Kid-Inclusive Budgeting: Age-appropriate involvement. 10-year-old managed $20/week allowance via envelope system. Learned delayed gratification alongside dad. Obstacles: Emotional spending spikes during co-parenting conflicts. Guilt over self-care spending. Fear of saying “no” to kids’ requests. Relapsed twice into old patterns during holidays. Resolution: Created “Conflict Response Protocol”: When triggered, wait 24 hours before any non-essential purchase. Journal emotions instead of spending. Celebrated small wins publicly with kid (“We saved $50 this week—that means extra park time!”). Therapy helped process resentment; budget became tool of empowerment, not punishment. Key Takeaway: Trauma-informed budgeting acknowledges emotional drivers. Self-care isn’t luxury; it’s sustainability. Involving children builds resilience and shared responsibility. Progress includes setbacks; compassion enables persistence.
Case Study 4: The Retiree Navigating Fixed Income
Profile: Linda, 68, Widow. Social Security + Pension: $3,200/month. Savings: $180,000. Initial State: Terrified of outliving money. Overly restrictive budget caused isolation and depression. Avoided social activities, skipped medications to save copays, hoarded resources unnecessarily. Adult children worried about her mental health. The Intervention:
- Abundance Reframe: Calculated safe withdrawal rate (4% rule adjusted for longevity). Discovered she could safely spend $600/month beyond essentials without depleting principal prematurely.
- Joy Allocation: Created “Connection & Wellness” category ($400/month) for senior center lunches, library programs, gentle yoga class. Framed as health maintenance, not frivolity.
- Healthcare Optimization: Reviewed Medicare Part D plan; switched to better coverage reducing copays by $80/month. Applied for prescription assistance programs.
- Legacy Planning Integration: Allocated $100/month to grandkids’ education fund. Transformed saving from fear-based hoarding to purposeful giving. Obstacles: Deep-seated scarcity mindset from Great Depression-era upbringing. Resisted spending on herself. Distrusted financial calculations. Grief complicated decision-making. Resolution: Worked with elder-focused financial counselor who validated fears while providing data. Started small: $20/week coffee with friend. Positive experiences rewired associations between spending and safety. Joined widow support group where budgeting tips were shared without shame. Within 6 months, reported improved mood and stronger family connections. Key Takeaway: Retirement budgeting balances preservation with quality of life. Scarcity mindset requires compassionate restructuring. Social connection is a legitimate budget category. Purpose transforms saving from fear to legacy.
15. Frequently Asked Questions (25+ FAQs)
Addressing common concerns prevents abandonment. These answers synthesize behavioral science, practical experience, and expert consensus.
Q1: How long does it take to build a budget that actually sticks?
A: Expect 3–6 months of active adjustment. Months 1–2 involve data gathering and system testing. Months 3–4 focus on habit formation and friction reduction. Months 5–6 refine based on real-world feedback. Sticking isn’t binary; it’s progressive mastery. Celebrate micro-wins weekly.
Q2: What if I overspend early in the month? Do I give up?
A: Never give up mid-month. Immediately assess: Can I cover it from Buffer? If yes, do so and note the trigger. If no, reduce another discretionary category now. Conduct post-mortem: Was it emotional? Unexpected? System flaw? Adjust next month’s allocation or add friction. One slip doesn’t erase progress.
Q3: Should I include my partner’s income if we’re unmarried?
A: Only if you share financial responsibilities. Separate finances require separate budgets with coordinated sinking funds for shared expenses (rent, utilities). Joint finances demand unified budget regardless of marital status. Clarity prevents resentment. Discuss expectations explicitly.
Q4: How do I budget for irregular bonuses or tax refunds?
A: Treat windfalls as anomalies, not income. Pre-decide allocation before receipt (e.g., 50% debt, 30% savings, 20% fun). Deposit directly into designated accounts upon arrival. Never let windfalls sit in checking—they’ll vanish. Windfalls accelerate goals; they don’t justify permanent lifestyle upgrades.
Q5: Is it okay to have a “fun money” category with no tracking?
A: Yes, within limits. Allocate a fixed monthly amount ($50–$200) for guilt-free spending. No receipts needed. This preserves autonomy and prevents rebellion. But cap it strictly. Unlimited fun money defeats budgeting purpose. Track only if you consistently exceed cap.
Q6: How do I handle shared expenses with roommates fairly?
A: Use Splitwise or similar app for transparency. Reimbursements are income in your personal budget only when received. Never budget anticipated reimbursements. Set clear payment deadlines. Rotate bill-paying responsibility monthly to avoid imbalance. Document agreements in writing.
Q7: What if my job pays biweekly but bills are monthly?
A: Create a “Bill Pay Holding” account. Deposit both paychecks here. Schedule all bill payments from this account on consistent dates (e.g., 1st and 15th). Transfer remaining funds to spending account after bills clear. This decouples pay frequency from expense timing.
Q8: Should I track petty cash purchases under $5?
A: Initially, yes—to establish baseline awareness. After 2 months, if pattern is stable, estimate monthly average ($30–$50) and budget lump sum. Stop tracking individual pennies. Focus energy on high-variance categories. Perfectionism kills consistency.
Q9: How do I budget when starting a new job with unknown expenses?
A: Use industry benchmarks temporarily. Research average costs for commuting, work attire, meals. Build conservative estimates. Track aggressively first 3 months. Adjust categories based on actuals. New jobs often reveal hidden costs (parking, professional dues); anticipate them.
Q10: Can I use credit cards responsibly while budgeting?
A: Absolutely—if paid in full monthly. Treat credit card payments like cash transactions. Log purchases immediately. Set autopay for statement balance. Never carry revolving debt. Rewards are bonus, not justification. If you can’t pay full balance, switch to debit/cash until discipline is proven.
Q11: How do I explain budget constraints to kids without causing anxiety?
A: Frame positively: “We’re choosing to save for [goal] instead of buying [item].” Involve them in age-appropriate trade-offs. Avoid phrases like “we can’t afford it.” Say “that’s not in our plan right now.” Model thoughtful decision-making. Kids learn security from predictability, not perfection.
Q12: What if my spouse refuses to participate in budgeting?
A: Start with your own finances. Lead by example. Share wins without preaching. Invite collaboration on one shared goal (vacation, debt payoff). Offer to handle logistics if they contribute input. Respect autonomy while demonstrating value. Professional mediation may be needed if resistance stems from trauma.
Q13: How often should I review and adjust my budget?
A: Weekly check-ins (20 mins) for reconciliation. Monthly deep dives (60 mins) for trend analysis and category adjustments. Quarterly reviews for goal alignment and tool evaluation. Annual overhaul for life changes (job, baby, move). Flexibility prevents rigidity-induced failure.
Q14: Should I budget for inflation separately?
A: Build inflation into baseline estimates. Review historical spending quarterly; if category averages rise 3–5%, adjust proactively. Don’t wait for deficit. Inflation is predictable; surprise isn’t. Update sinking fund targets annually based on actual cost increases.
Q15: How do I handle seasonal spending spikes (holidays, back-to-school)?
A: Sinking funds are designed for this. Calculate annual cost ÷ 12 = monthly contribution. Start saving January for December holidays. Back-to-school? Begin May. Smooth peaks across 12 months. Never rely on credit for predictable seasonal expenses.
Q16: Is zero-based budgeting necessary for everyone?
A: No. ZBB suits detail-oriented personalities and tight-margin situations. Others thrive with percentage-based (50/30/20) or values-based frameworks. Match method to temperament. Hybrid approaches often work best: ZBB for fixed/debt, flexible caps for variable spending.
Q17: How do I rebuild trust after hiding spending from my partner?
A: Full transparency immediately. Share all accounts/passwords. Establish joint visibility tools (shared app, weekly meetings). Acknowledge harm without defensiveness. Rebuild through consistent honesty over time. Trust repairs slower than it breaks. Professional counseling recommended.
Q18: What if I lose my job while paying off debt?
A: Pause aggressive debt payoff immediately. Preserve cash flow for Four Walls. Use emergency fund for essentials. Contact creditors for hardship programs (many offer temporary reduced payments). Resume acceleration only when income stabilizes. Survival precedes optimization.
Q19: Should I budget for charitable giving?
A: Yes, if aligned with values. Treat donations as intentional allocations, not afterthoughts. Automate recurring gifts. Track impact alongside financial metrics. Giving reinforces abundance mindset. Cap at sustainable percentage (typically 5–10%) to avoid compromising stability.
Q20: How do I handle gift-giving pressure from family/friends?
A: Set boundaries kindly: “Our budget allows $X for gifts this year.” Offer non-monetary alternatives (time, skills, homemade items). Propose gift exchanges or donation drives. True relationships respect financial boundaries. Generosity isn’t measured by price tag.
Q21: Can I retire early if I stick to this budget?
A: Budgeting enables FIRE (Financial Independence, Retire Early) by maximizing savings rate. But early retirement requires additional strategies: geographic arbitrage, side hustles, investment optimization, healthcare planning. Budget is foundation; comprehensive plan is structure. Consult fiduciary advisor for personalized roadmap.
Q22: How do I stay motivated during slow debt payoff phases?
A: Visualize progress: Thermometer charts, debt-free countdown calendars. Celebrate milestones (every $1k paid). Join accountability communities. Remind yourself of “why” written during setup. Focus on behaviors controlled (spending choices), not outcomes delayed (balance reduction). Momentum builds invisibly before becoming visible.
Q23: Should I include pet expenses in my budget?
A: Absolutely. Pets are family members with real costs. Budget for food, vet care, grooming, insurance, emergencies. Create pet sinking fund for unexpected medical bills. Neglecting pet costs leads to crisis spending or compromised care. Responsible ownership includes financial planning.
Q24: How do I transition from survival budgeting to wealth building?
A: Once Four Walls secured and high-interest debt eliminated, redirect freed cash flow systematically. Increase retirement contributions incrementally. Fund taxable brokerage accounts. Explore tax-efficient strategies. Upgrade skills for income growth. Wealth building is budget evolution, not replacement.
Q25: What’s the #1 mistake people make when starting?
A: Setting unrealistic restrictions. Starvation budgets trigger rebound spending. Start with accurate baselines, then optimize gradually. Sustainability beats intensity. Permission to enjoy life within parameters ensures long-term adherence. Perfection is enemy of progress.
Q26: How do I handle financial shame when reviewing past spending?
A: Shame paralyzes; curiosity liberates. Approach data neutrally: “What was I needing then?” Replace judgment with understanding. Past spending served a purpose (comfort, connection, coping). Honor that need while designing healthier fulfillment methods. Compassion fuels change; shame sustains cycles.
Q27: Should I hire a financial coach or DIY?
A: DIY works for self-motivated learners with moderate complexity. Coaches excel for trauma recovery, complex situations (divorce, business owners), or accountability gaps. Vet credentials (CFP, AFCPE). Cost-benefit analysis: If coach accelerates debt payoff by 2 years, fees may be justified. Trial sessions help assess fit.
16. Final Verdict & Key Takeaways
Building a realistic budget that sticks isn’t about achieving mathematical perfection. It’s about creating a resilient system that honors your humanity while advancing your financial freedom. After exploring psychology, methodology, troubleshooting, and real-world applications, the verdict is clear: Success lies in adaptive consistency, not rigid compliance.
Core Principles Recap
- Psychology Precedes Math: Understand your money scripts, pain of paying, and decision fatigue triggers before touching spreadsheets. Systems fail when they ignore human nature.
- Data Drives Decisions: Conduct thorough financial autopsies. Granular categorization reveals true patterns. Baseline accuracy prevents setting yourself up for failure.
- Method Matches Personality: Zero-based, 50/30/20, envelope, values-based—choose what fits your cognition and lifestyle. Hybrid models often win. Flexibility within framework sustains engagement.
- Sinking Funds Prevent Surprises: Irregular expenses destroy budgets. Smooth annual costs across 12 months. Buffer categories absorb shocks. Predictability breeds confidence.
- Debt Strategy Aligns With Temperament: Avalanche saves money; snowball saves sanity. Choose based on psychological needs, not just math. Integrate repayment dynamically into cash flow.
- Friction Design Beats Willpower: Make good choices effortless, bad choices difficult. Automation, pre-commitments, and environmental tweaks sustain behavior when motivation fades.
- Resilience > Perfection: Expect variances. Monthly resets, course corrections, and compassionate self-talk maintain momentum. Burnout recovery protocols prevent abandonment.
- Wealth Building Evolves From Stability: Secure foundations first, then optimize. Tax efficiency, asset allocation, and income scaling transform budgets from survival tools to prosperity engines.
- Relationships Require Intentionality: Transparent communication, autonomy allowances, and shared vision prevent money conflicts. Financial intimacy strengthens partnerships.
- Lifelong Learning Adapts to Change: Budgets aren’t static documents. Life stages, economic shifts, and personal growth demand regular reassessment. Curiosity sustains relevance.
Your Next Steps
- Conduct Your Financial Autopsy Today: Gather 3–6 months of statements. Categorize ruthlessly. Calculate true income and spending baselines.
- Choose Your Framework This Week: Experiment with one method for 30 days. Adjust based on friction points. Commit to weekly money dates.
- Implement One Behavioral Hack Immediately: Unsubscribe from 5 marketing emails. Delete 1 shopping app. Institute 48-hour rule for non-essentials. Small wins build confidence.
- Create Your First Sinking Fund: Identify one upcoming irregular expense. Calculate monthly contribution. Open sub-account or tag today. Experience proactive peace.
- Schedule Your First Accountability Check-In: Tell one trusted person your goal. Set date for progress review. External commitment increases follow-through.
The Bigger Picture
A realistic budget is more than numbers—it’s a declaration of self-respect. It says: My future matters. My peace matters. My dreams matter. It transforms money from source of anxiety to instrument of agency. You will stumble. You will recalibrate. You will grow. Each iteration brings deeper alignment between values and resources.
Remember Sarah, Marcus & Elena, James, and Linda. Their struggles mirror yours. Their breakthroughs are possible for you. They didn’t achieve perfection; they achieved persistence. That’s the metric that matters.
Close this guide. Open your bank statement. Begin. Not tomorrow. Not Monday. Now. Your financial freedom isn’t found in flawless execution—it’s forged in faithful continuation. Build realistically. Stick relentlessly. Live abundantly.